1926 E. Fort Lowell Rd Suite 100
Tucson, AZ 85719
Contact Us
Mon - Thurs: 9:00 - 5:00 AZ
Fri: 9:00 - 3:00 AZ
For Tucson professionals, business owners, and affluent families with $250K–$1M+ who need coordinated investment management, tax strategy, estate planning, and risk management—not just another portfolio.
Fee-Based Fiduciary
20+ Years in Tucson
Tucson-Based
Transparent Fees
Most wealth doesn’t disappear in market crashes.
It leaks slowly—through uncoordinated tax decisions, overlapping fund fees, concentration risk no one’s tracking, and withdrawal timing mistakes that compound over decades.
These aren’t dramatic failures. They’re invisible drags that quietly erode what you’ve spent years building. And the problem? You can’t see them unless someone’s looking at the whole picture.
When it comes to wealth management, here’s what we see in Tucson:
A medical professional exercises stock options without modeling the tax impact—pushing them into a higher bracket and triggering Medicare surcharges they didn’t budget for.
A business owner holds three separate portfolios with overlapping positions—paying fees on duplicate exposures and taking more risk than they realize.
A dual-income couple coordinates nothing between their two 401(k)s—one conservative, one aggressive—creating a portfolio that doesn’t actually match their joint risk tolerance or timeline.
A retiree withdraws from the wrong account first—leaving tax-advantaged growth on the table and paying more to the IRS than necessary over the next two decades.
None of these are reckless moves. They’re just isolated decisions made without a coordinated strategy. And over time, the leaks add up.
Wealth management replaces fragmentation with a system. It connects investments, taxes, estate updates, and risk management into one strategy—reviewed regularly, stress-tested against real scenarios, and managed by a fiduciary who sees what others miss.
Because the wealth you keep matters more than the wealth you accumulate.

Wealth management is the coordinated oversight of investments, taxes, estate planning, risk management, and cash flow, designed to grow and protect your assets across decades.
It’s not portfolio management alone. And it’s not a commission-based advisor selling you the product with the highest payout.
Wealth management means every financial decision reinforces the next. One strategy built around your specific situation, where your portfolio allocation reflects your tax outlook, your withdrawal plan accounts for your estate goals, and when something changes (e.g., your income, your family, the law), the rest adjusts with it.
Most people who benefit from wealth management aren’t missing a good investment strategy, but someone who sees how all of it fits together.
“It’s just for the ultra-wealthy.”
If you have $500K–$2M+ in investable assets and any complexity—business ownership, stock compensation, multi-state tax questions—wealth management applies to you. And if you’re at the higher end of that range, our high-net-worth financial advisor service is built specifically for you.
“It’s only about investing.”
Investment allocation is critical, but it follows your tax strategy, estate intent, and risk tolerance.
“One portfolio fits all.”
Generic model portfolios ignore your specific timeline, tax bracket, spending comfort, and risk capacity.
“Set it and forget it.”
Markets shift. Tax laws change. Businesses get sold. Wealth management is ongoing—reviewed regularly and adapted as life evolves.
In Southern Arizona, wealth management takes on its own texture. Business transitions, stock compensation packages, snowbird tax questions, and estate planning across state lines all create layers that a one-size-fits-all approach can’t address.
1. Business owners and practice transitions
Exit planning starts years before the sale with tax-efficient structuring, equity compensation strategy, and cash flow modeling.
2. High-income professionals
Doctors, engineers, executives—managing RSUs, stock options, or deferred compensation while balancing growth with tax efficiency requires coordinated planning.
3. Dual-income families near retirement
Consolidating scattered 401(k)s, coordinating spousal claiming strategies, and unifying tax-bracket management turns fragmentation into a clear path forward.
4. Tucson snowbirds and new residents
Splitting time between states raises residency questions that affect state taxes and filing requirements. Arizona’s flat income tax offers advantages—but only with proper coordination.
5. Generational wealth planning
Protecting what you’ve built means coordinated estate updates, trust funding reviews, and family conversations about values—all aligned with your wealth strategy.
Wealth management turns isolated decisions into a coordinated strategy. Here’s what we do with you—tactically and transparently.
1. Portfolio Design & Ongoing Management
Custom allocation based on your risk tolerance, timeline, and goals—not a cookie-cutter model. Diversification across asset classes, disciplined rebalancing, and stress testing keep your portfolio aligned with what you need. We focus on efficiency: visible fees, minimized tax drag, and risk-adjusted returns.
2. Multi-Year Tax Strategy
We create an annual tax roadmap that looks beyond April 15. Bracket management, capital gains harvesting, Roth conversion windows, and coordination with your CPA—all with a view five to ten years ahead.
3. Risk Management & Wealth Protection
We review insurance coverage and analyze concentration risk—single stock positions, real estate holdings, business equity. We stress-test your portfolio against market crashes, inflation spikes, and sequence-of-returns risk.
4. Estate & Legacy Coordination
We review beneficiaries, check titling alignment, and verify trust funding. We coordinate with estate attorneys to ensure legal structures reflect your current wishes.
5. Cash Flow & Spending Strategy
We model sustainable withdrawal rates, set guardrails for spending flexibility, and coordinate all income sources into one clear picture. Decision rules help you avoid emotional reactions when markets get volatile.
6. Behavioral Coaching & Ongoing Reviews
We meet regularly to review progress and adjust strategy. Education comes first—you understand why before we recommend what. This prevents panic selling and other behaviors that quietly erode wealth.
What You Receive:
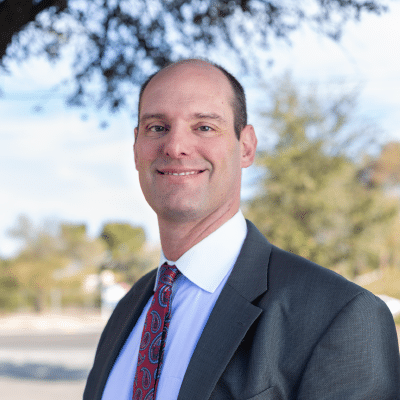
Alex Parrs
Partner | CFA, CFP®, ChFC, CFS, CASL
Alex is a wealth manager with over 15 years of experience specializing in retirement planning, wealth preservation, and portfolio management. A CFA and CFP® professional, he enjoys cooking, playing basketball, and spending time with his wife and three children.
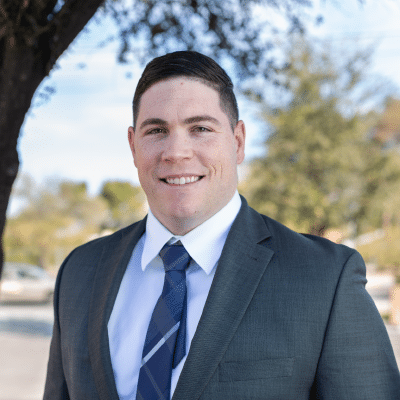
David Renzi
Senior Wealth Manager | CFA
David is a wealth manager with over ten years of experience specializing in financial goal planning, wealth preservation, and portfolio management. A CFA charterholder, he enjoys volunteering, outdoor camping, and spending time with his wife Karem and their family.
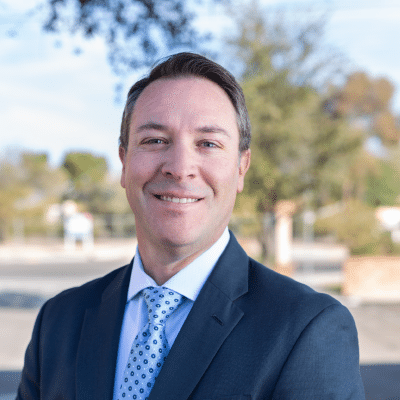
Dan Nentl
Partner | CFS, ChFC
Dan is a wealth manager with extensive professional experience specializing in financial goal planning, wealth preservation, and tax optimization. A ChFC professional, he enjoys community volunteering, coaching youth sports, and spending time with his wife Jules and their children.
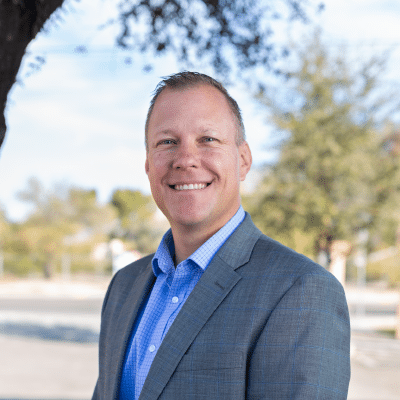
Robin Dolezal
Partner | CFP®
Robin is a wealth manager with extensive professional experience specializing in financial goal planning, wealth preservation, and tax optimization. A CFP® professional, he enjoys community volunteering, traveling, cooking, and spending time with his wife Melissa and their two sons.

A successful local business owner had approximately $500,000 in retirement accounts split between two separate investment advisors. Despite good income and disciplined saving, they couldn’t get a clear answer on whether they were on track for retirement. One advisor would recommend one thing; the other something completely different. Neither could see the complete picture, and when one advisor wanted to trigger significant taxes for commission-based products, the fragmentation became impossible to ignore.
We consolidated everything under Ironwood’s fee-based fiduciary structure, inventorying every account and holding to see the complete financial picture for the first time. We identified tax inefficiencies and risk imbalances neither previous advisor had addressed. Then we built a comprehensive financial plan—assessing retirement timeline, modeling tax projections, and coordinating portfolio strategy with their business priorities. We eliminated conflicts of interest and established one point of contact who could coordinate all decisions without competing agendas.
They avoided unnecessary tax triggers from commission-driven recommendations and reduced total advisory costs through consolidated management. For the first time, their portfolio was properly balanced across all accounts with appropriate risk levels. Most importantly, they confirmed they were on track to retire at their target age—a question they’d asked both previous advisors but never received a clear answer about. As they shared with us: all the pieces were finally working together.
Read the full story:
Not everyone needs a wealth manager—and we’ll tell you honestly if that’s you. But if any of these sound familiar, wealth management can help:
You have $500K–$2M+ in investable assets (or complex situations with lower balances)
You want coordinated strategy across investments, taxes, estate planning, and risk
You’re a business owner, professional, or dual-income household with moving parts
You want a fiduciary advisor—not someone earning commissions on products
You prefer ongoing reviews so your strategy adapts as life changes
You’re in Tucson or want a local advisor who understands Arizona considerations
If you’re under $250K and prefer managing investments yourself, you may not need us yet. But if you have complexity and want coordination, wealth management brings everything into one strategy.
Why Tucson Families Trust Ironwood for Wealth Management
Choosing a fiduciary financial planner in Tucson shouldn’t feel like a leap of faith. Here’s what sets Ironwood apart when it comes to comprehensive financial planning:
Fiduciary, fee-based structure
We’re legally required to act in your best interest—no product quotas. Our fee structure aligns with your portfolio growth.
Efficiency-focused approach
We examine visible fees, tax drag, and risk-adjusted returns—especially critical for portfolios over $250K.
Customized, not cookie-cutter
Your portfolio is built for your situation—not assigned from a model shared with thousands of others
Risk-first philosophy
We start with risk assessment and build allocation around what you need. Preservation matters as much as growth when you have something to protect
Behavioral coaching
Market volatility triggers emotional decisions. We provide perspective and frameworks that help you stay the course
Same advisor, long-term
You work with the same person who knows your story, your family, and your concerns.
Transparent pricing
You know what you pay and why, in writing. No hidden costs or surprises
20+ years of local expertise
Tucson realities—Arizona’s flat tax, snowbird considerations, business transitions—are built into our approach.
In short: We’re not here to sell products. We’re here to coordinate investments, taxes, income, risk, and estate details into a plan you can live with—updated regularly, taught clearly, and built around what matters to you.
Portfolio management focuses on investments—allocation, rebalancing, and performance. Wealth management integrates tax strategy, estate coordination, risk management, and cash flow planning, then aligns your portfolio to support them all.
Financial advisor’ is a broad title that can mean anything from a commission-based product seller to a fee-only fiduciary. Wealth management is a specific service model that coordinates your investments, tax strategy, estate planning, and risk management under a single, ongoing strategy. At Ironwood, we are fee-based fiduciary financial advisors who deliver wealth management, not just periodic investment advice.
No. Most clients have $500K–$2M+ in assets. If you have complexity—business ownership, stock compensation, multi-state considerations—wealth management applies to you.
How do your fees work? We typically charge a percentage-based fee on assets under management (AUM). We don’t usually charge separate planning fees. In rare cases, if an insurance product is recommended and implemented, we may receive a commission related to that product.
Yes. We work regularly with CPAs on tax timing and estate attorneys on beneficiary alignment. If you don’t have preferred professionals, we can introduce trusted Tucson options.
If you’re handling it well on your own, we’ll tell you—about one in four people we meet don’t need us. But if you want coordination across taxes, risk management, estate planning, and behavioral coaching, that’s where fees add value.
Regularly, with additional check-ins for life changes—business sales, market shocks, relocations, family transitions.
Ironwood does not directly manage or custody cryptocurrency. As fee-based fiduciary advisors, we focus on traditional, custodied investment structures such as equities, bonds, and diversified funds. If crypto holdings are part of your broader financial picture, we factor them into your overall wealth management and tax strategy conversations.
Yes, in many cases. Our wealth management services are designed for individuals and families with $500K to $2M+ in investable assets, particularly when your financial life includes some complexity: business ownership, stock compensation, multiple income sources, or estate planning needs. If you’re at the lower end of that range with a simpler situation, we’ll tell you honestly whether wealth management or a more focused planning engagement is the better fit.
You don’t need another portfolio—you need a coordinated strategy that connects investments, taxes, estate planning, and risk management so your wealth works for your life.
The easiest way to start is a short conversation with a fiduciary who will listen, assess your situation, and outline whether wealth management is the right fit—no sales pitch, no pressure.
What you can expect: clarity on priorities, a high-level view of your current efficiency, and honest guidance on next steps.

