1926 E. Fort Lowell Rd Suite 100
Tucson, AZ 85719
Contact Us
Mon - Thurs: 9:00 - 5:00 AZ
Fri: 9:00 - 3:00 AZ
For Tucson retirees and professionals who’ve spent decades building wealth and want to keep it safe
Fee-Based Fiduciary
20+ Years in Tucson
Tucson-Based
Transparent Fees
When you get close to retirement, your focus naturally shifts. You’ve spent decades working and saving, and your priority shifts from chasing growth to protecting what you’ve built.
You want:
To protect what you’ve worked for, here’s what you need to know:
Preserving wealth is simply about replacing worry with a clear, disciplined plan, so you can spend your retirement comfortably. Working with a financial advisor in Tucson helps you coordinate each of these areas so your savings stay protected.
Common Misconception: “Preserving wealth means putting everything in bonds or CDs and accepting low returns that barely keep up with inflation.”
The Reality: Preserving wealth is about balance: taking the right amount of risk for where you are in life, with a portfolio built to handle market storms without pushing you into emotional decisions. Growth still has a place.
Preserving wealth is about being able to spend with confidence, including:
Good preservation planning also keeps more of what you’ve earned in your pocket through careful tax planning, fewer unnecessary fees, and risk that’s managed on purpose.
Our job is to help you hold on to what you’ve built.
The Tucson advantage: Arizona has a 2.5% flat income tax, so more of your money stays with you than in high-tax states. Tucson’s lower cost of living and healthcare costs also give preservation strategies more room to be conservative while you keep your lifestyle.
But Tucson also has its own challenges:
Wealth preservation advice built for high-tax coastal markets doesn’t always fit Arizona. You need a strategy built for Tucson.
Here’s how we approach it, with the challenges Tucson families actually face in mind.
We start with how much risk you can actually handle. Then we build a diversified portfolio around your need for stability and stress-test it against market crashes, inflation spikes, and a bad stretch right after you retire. The goal is to avoid more volatility than you need to meet your goals.
Arizona’s 2.5% flat tax can create opportunities that other states don’t offer. We coordinate Roth conversions, the order you draw from each type of account, and the timing of capital gains to help lower your lifetime taxes. If you’re a snowbird, we also work through the multi-state tax issues that can catch people off guard.
Markets will drop. 2008 and the COVID crash did, and another one will come. When it does, we stay in touch to help you avoid panic selling, and regular check-ins during rough stretches help you stick to the plan when your instinct says to abandon it. This kind of guidance can matter as much as which investments you pick.
Many Tucson families have built up much of their wealth in one position: company stock, business ownership, or real estate. We help you spread that risk across different kinds of investments, and we plan the tax side carefully so the move doesn’t cost more than it should.
Healthcare costs in Tucson run lower than on the coasts, but Medicare still has gaps. We help you plan for what insurance doesn’t cover, so a large medical or long-term care expense is less likely to derail an otherwise well-funded retirement.
We work alongside your estate attorney so your investments, beneficiaries, and estate plan line up, and so estate taxes are considered as part of the plan.
Prices keep rising, and retirement can last a long time. We look at how your plan holds up if inflation runs higher than expected. Depending on your situation, we may look at Treasury Inflation-Protected Securities (TIPS, government bonds designed to adjust with inflation), real estate, or commodities, and weigh the risks of each against your goals.
“Money isn’t a scoreboard. It’s a tool to afford you comfort and build lasting family memories.”
– Dan Nentl, Partner | CFS, ChFC
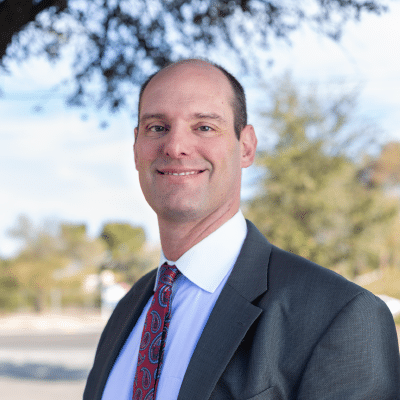
Alex Parrs
Partner | CFA, CFP®, ChFC, CFS, CASL
Alex is a wealth manager with over 15 years of experience specializing in retirement planning, wealth preservation, and portfolio management. A CFA and CFP® professional, he enjoys cooking, playing basketball, and spending time with his wife and three children.
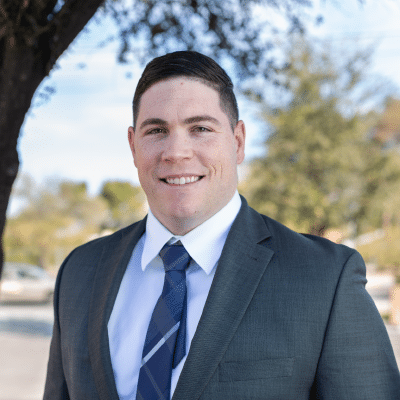
David Renzi
Senior Wealth Manager | CFA
David is a wealth manager with over ten years of experience specializing in financial goal planning, wealth preservation, and portfolio management. A CFA charterholder, he enjoys volunteering, outdoor camping, and spending time with his wife Karem and their family.
Dan Nentl
Partner | CFS, ChFC
Dan is a wealth manager with extensive professional experience specializing in financial goal planning, wealth preservation, and tax optimization. A ChFC professional, he enjoys community volunteering, coaching youth sports, and spending time with his wife Jules and their children.
Robin Dolezal
Partner | CFP®
Robin is a wealth manager with extensive professional experience specializing in financial goal planning, wealth preservation, and tax optimization. A CFP® professional, he enjoys community volunteering, traveling, cooking, and spending time with his wife Melissa and their two sons.
How Tucson Families Preserve Their Wealth with Ironwood

We work with Tucson retirees and professionals who’ve built significant wealth but struggle with the shift from accumulation to preservation. Common situations include portfolios concentrated in single positions, uncertainty about appropriate risk levels for retirement, and anxiety during market volatility.
Our wealth preservation approach helps families diversify concentrated holdings in tax-efficient ways, right-size portfolio risk for their stage of life, and develop withdrawal strategies designed to weather market downturns. The ongoing behavioral coaching we provide often matters as much as the investment strategy itself, keeping clients disciplined during turbulent periods.
Families most often tell us the greatest benefit is reduced anxiety, confidence in their strategy, and the ability to spend comfortably in retirement without constantly worrying about running out of money.
A Tucson dentist had turned a modest investment into a multi-million-dollar stock position. Most of their retirement wealth was in that one stock, and they checked the price several times a day. Despite significant assets, they kept asking: “Can I retire comfortably?”
We started with what they actually needed to live on in retirement. Then we asked a simple question: would they rather keep a portfolio they worried about constantly, or give up the chance at maximum returns for a diversified one they didn’t have to watch? They chose diversification. We built a tax-conscious plan to move most of the stock into a balanced portfolio, and we meet with them regularly throughout retirement.
They stopped checking the stock price all day and could think about retirement without constant worry. Their plan is now built around the life they want in retirement.
Read the full story:
From $3 Million in Daily Anxiety to True Retirement Peace of Mind
Individual results vary. This case study is not a guarantee of future outcomes.
Wealth preservation tends to fit Tucson-area individuals and families who:
Are within 10 years of retirement or already retired
Worry more about losing money than about maximizing growth
Have concentrated positions in company stock, a business, or real estate
Feel anxious when markets get volatile
Want their wealth to last through a retirement that could run 20 to 30 years or more
Want tax planning built into their investment strategy
Prefer fee-based fiduciary advice over commission-based product sales
Want ongoing guidance and coaching when times are uncertain
Fee-Based Fiduciary
We’re legally required to put your interests first. No commissions means no incentive to take unnecessary risks with your wealth. Our compensation aligns with your goals, protecting and preserving what you’ve built.
Risk-First Methodology
We start with risk assessment, not performance projections. We don’t gamble with your life’s work chasing returns you don’t need. Our approach prioritizes protection first.
20+ Years Tucson Experience
We understand Arizona’s tax advantages, local cost of living, and the specific challenges Tucson retirees face, from snowbird complications to small business concentration risk.
Behavioral Coaching
We keep you from making emotional decisions during market downturns. This discipline of preventing panic when markets drop often matters more than investment selection for long-term wealth preservation.
Preservation doesn’t mean zero growth. It means right-sizing risk for your stage of life. We still pursue returns, just without the unnecessary volatility that could derail your retirement plan. The goal is sustainable growth with appropriate protection.
This is called sequence-of-returns risk, and it’s exactly what preservation strategies protect against. We stress-test your portfolio against this scenario and build in buffers so market timing doesn’t devastate your retirement income.
Absolutely. Preservation and income aren’t opposites. We design withdrawal strategies that provide reliable income while protecting your principal through diversification, tax efficiency, and strategic rebalancing.
Not at all. We help clients recover from losses by preventing future emotional decisions and building disciplined strategies going forward. What you do next matters far more than what has already happened.
Being overly conservative often means returns that don’t keep pace with inflation, slowly eroding purchasing power. True preservation means strategic balance: enough growth to maintain lifestyle, enough protection to weather downturns, and enough tax efficiency to keep more of what you earn.
There’s no single best way. It depends on when you’ll need the money, how much income you need from it, and what you’re paying in taxes. For most people, it starts with owning a mix of investments that doesn’t take more risk than you need, and taking money out of your accounts in an order that takes taxes into account. It also means planning for healthcare and long-term care costs, and having estate documents and beneficiaries that say what you want.
We look at all of these together, because a change in one usually affects the others.
Start with how they get paid and whether they’re a fiduciary all the time, which means they have to put your interests first. Then look them up. You can check any advisor’s record, including complaints and their Form ADV, at adviserinfo.sec.gov. If they say they’re a CFP®, you can confirm that on the CFP Board’s website.
We’re a fee-based fiduciary firm, and you’re welcome to read our Form ADV Part 2A before we ever meet.
No. Wealth preservation is for anyone with savings they want to protect, including retirees whose money is mostly in retirement accounts and their home, and sometimes a local business. A bad market or a badly timed withdrawal can hurt just as much when the savings are smaller. Preserving wealth is about protecting what you’ve saved and what you’ll need.
Our annual fee is based on assets under management, starting at 1%. As account sizes increase, the fee rate decreases. Our official minimum is $250,000, but our average account is above $1,000,000.
No. If you’ve built up savings you want to protect, it matters at 45 as much as at 75. The sooner you look at your risks, your taxes, and anything that makes up too much of your savings (like one stock), the more options you have.
Stop worrying about market volatility and start protecting what you’ve built.
No pressure • No product sales • Just honest guidance about protecting your wealth
Ready to move from anxiety to confidence?
Our wealth preservation review will show you exactly how to safeguard what matters most and build a strategy designed for the retirement you’ve earned.
Schedule your consultation today.


